Cash App

Screenshots
Details
- Rating
- 453.14K reviews
- Version
- 5.35.0
- Developer
- Block, Inc.
Analysis by Norviv
I think Cash App makes the most sense when you want everyday money tasks close at hand rather than spread across several services. It is a finance app from Block, Inc., and its combination of person-to-person payments, banking tools, investing and Bitcoin gives it a wider reach than a simple bill-splitting wallet. That breadth is useful, but it also means I would treat it as a convenient financial hub, not automatically as a replacement for every account or service I use.
What the current app is suited to
The app is free, rated for Everyone, and its current version is 5.35.0. It has been available since October 15, 2013, and the Android minimum operating system is version 10. Its 4.7 average across around 4.1 million ratings, with roughly 453,000 written reviews and over 100 million installs, suggests that it has become a familiar option for many people. Those figures indicate reach, not a guarantee that every feature or transaction will suit your circumstances.
The practical appeal is having several money activities in one place. I would consider it for sending a friend my share of a meal, receiving money from a roommate, or keeping an app balance for spending. If you also want to explore investing or Bitcoin, having those options alongside payments can reduce the need to switch between apps. The trade-off is that a broader menu does not make every part as comprehensive as a dedicated bank or investment service.
Guides and News About Cash App
Have you ever needed to send money to a friend or split a bill at dinner without the hassle of dealing with cash? If so, you've probably heard of Cash App. This nifty little app is a game-changer when it comes to managing your money on the go.
Getting Started with Cash App
Diving into Cash App is like jumping into a pool of convenience. Setting it up is a breeze. All you need is a smartphone and a few minutes to spare. You download the app, link your bank account or a debit card, and voilà! You're ready to start sending and receiving money in no time.
The user interface is super friendly. Trust me; even if you're not tech-savvy, you'll find it easy to navigate. Everything is laid out in a way that just makes sense. Plus, the app's design is sleek and modern, giving it a fresh vibe.
Features You’ll Love
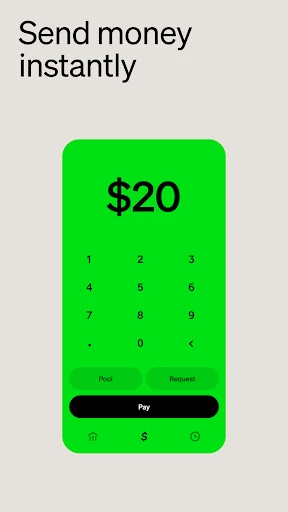
One of the standout features of Cash App is its simplicity. Whether you’re paying your share of brunch or receiving rent from a roommate, it’s all just a few taps away. What’s more, you can choose to keep a small balance on the app itself or cash out directly to your bank account.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Now, let's talk about the Cash Card. This is a customizable debit card linked to your Cash App balance, and it’s perfect for those who want to spend their app funds directly. Plus, you can personalize it with a signature or drawing, which is a fun touch!
Making payments work smoothly
A useful habit is to check the recipient details before confirming a payment. A quick transfer can feel effortless, but that convenience also makes it worth slowing down for a second to verify who is receiving the money and how much you are sending. For a regular shared expense, agreeing on the amount and the payment note with the other person first can prevent confusion later.
For a realistic example, imagine splitting dinner with a friend who paid the full bill. You can send your portion from your phone and keep the record in the app, rather than trying to remember who owes what after the evening. For rent or another recurring household cost, I would still agree on a consistent schedule and keep any important agreement outside the payment itself; a transfer record helps track money, but it is not a substitute for clear communication.
Cash App is most appealing if the people you pay already use it and you value a quick, direct workflow. If your friends or household rely on a different payment service, asking everyone to adopt another app may add friction rather than remove it. In that situation, the service your group already uses—or a bank transfer that fits everyone’s routine—can be the more practical choice.
Security and Peace of Mind
When it comes to handling money digitally, security is a big deal. Thankfully, Cash App takes this seriously. It offers features like two-factor authentication and instant notifications for every transaction. You can also pause your Cash Card if you misplace it, so you don’t have to worry about unauthorized spending.
But it’s not just the technical security that gives peace of mind; it’s the app’s transparency too. Every transaction is recorded in a clear, easy-to-understand manner, so you always know where your money went.
Everyday safeguards and useful habits
I would enable the available sign-in protections and pay attention to transaction notifications rather than treating them as background noise. A prompt can help you spot activity you do not recognize while it is still fresh in your mind. If the Cash Card is misplaced, pausing it is a sensible immediate step; I would also review recent activity and take the appropriate next steps through the app instead of assuming that a pause resolves every concern.
Another practical point is to decide what role the in-app balance should play. Keeping money there can make it handy for spending through the Cash Card, while cashing out to a bank account keeps your everyday funds within your usual banking setup. I would avoid letting convenience alone decide where a larger amount sits: think about how quickly you may need the money and whether you prefer to manage it through your bank.
Some Extra Perks
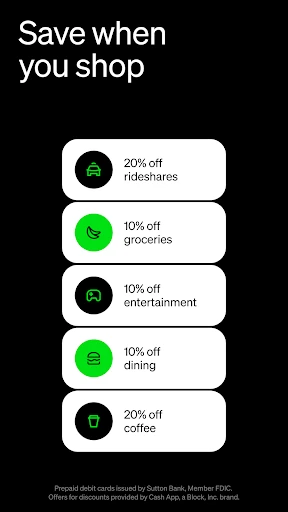
Another cool feature is the Boost program. It offers discounts at various retailers and restaurants when you use your Cash Card. Who doesn’t love saving a few bucks while grabbing a coffee or a bite to eat?
And for those dabbling in investments, Cash App allows you to buy and sell Bitcoin. It's a simple way to dip your toes into the world of cryptocurrencies without needing a separate platform.
Where the all-in-one approach has limits
The payment, card, investing and Bitcoin options make the app feel more versatile than a basic peer-to-peer wallet. Still, convenience should not be mistaken for depth. Someone who wants extensive banking services, detailed investment research, or a dedicated cryptocurrency environment may prefer specialist products designed around those needs. I see Cash App as a useful starting point for straightforward tasks, not a reason to move every financial decision into one interface.
Bitcoin also deserves a deliberate approach. The fact that buying and selling is accessible does not make it a low-risk place to park money or a substitute for understanding price swings. If you are curious, decide in advance whether you are experimenting with a small amount you can afford to expose to volatility, and do not let an easy purchase flow stand in for research.
Cash Card discounts are best treated as a possible bonus, not the reason to spend. Before changing a purchase decision for a Boost, I would check whether the offer genuinely fits something I already planned to buy. A discount that encourages an unnecessary purchase is not a saving, and the card’s convenience matters more than chasing every promotion.
Even though Cash App is a fantastic tool, it’s not without its quirks. Sometimes, the app might feel limited compared to a full-fledged banking app. However, for everyday transactions and peer-to-peer payments, it does the job beautifully.
How it fits beside banks and specialist apps
Compared with a conventional bank app, Cash App puts social payments and a Cash Card experience closer to the center. That can be more natural when the task is paying a friend or spending an app balance. A bank’s own app is often the better home for people who want their primary account and broader banking relationship managed in one place. I would choose based on the job, rather than assume one has to replace the other.
Compared with a payment-only wallet, Cash App’s investing and Bitcoin options offer more variety, but they can also make the app feel less focused. If all you need is an occasional transfer, a simpler service may be enough. If you use several of its functions, the convenience of a single account may justify keeping it, provided you remain comfortable with its limits and keep track of where your money is held.
One useful way to avoid muddling those roles is to think of the app in separate lanes: money sent to people, money held for card spending, and money used for investing or Bitcoin. Before moving funds, I would pause to identify which lane the transaction belongs to and what I expect to do next. That small check makes it easier to notice when a balance intended for day-to-day purchases is being treated like long-term savings.
Who I would recommend it to
I would recommend trying Cash App if you regularly split costs with people who already use it, want a quick way to move money between friends, or like the idea of linking a card to an app balance. It may also suit someone curious about investing or Bitcoin who wants those options alongside payments, as long as they understand that accessible controls do not remove financial risk.
I would be more cautious if you need a primary banking service with a broad set of account-management tools, prefer to keep all financial activity with one established bank, or want specialist investment features. It may also be a poor fit if your circle uses another payment method or you do not want to manage an additional balance. In those cases, your bank or a service already used by your contacts could make everyday transactions simpler.
Before relying on it for an important payment, I would make sure I understand the recipient flow, the balance I am using, and the available route for moving money back to my bank. For a first use, a modest transfer to someone I know is a more comfortable way to learn the interface than making a large or time-sensitive payment. That is not a special requirement; it is simply a sensible way to get familiar with any financial app.
What its evolution tells me—and what to watch
Cash App has been around since 2013, and version 5.35.0 is the current version considered here. That gives me a long-running product with a substantial audience, but a version number on its own does not tell me what changed in a particular release. I would not assume that a specific feature was newly added or improved without a clear release note. For existing users, the practical point is to keep the app current through the usual update process and check its screens directly when a familiar workflow looks different.
As the app continues to develop, I would watch for changes that affect the parts people rely on most: how clearly it presents payment details, how easy it is to manage the Cash Card, and whether money movement remains understandable when the app offers several financial activities together. Those are useful things to assess during normal use, not promises about future features. If the interface changes, I would take a moment to review the payment amount and destination before confirming rather than relying only on muscle memory.
A common question is whether it can replace a bank account. My view is that it can handle useful everyday tasks, but that does not make it the right sole account for everyone; people who need broader banking features should compare it with their bank’s services. Another natural question is whether Bitcoin belongs in the same app as payments. It can be convenient to have both available, but I would keep the decision to buy separate from routine transfers and consider the risk on its own terms.
People also wonder whether the app is worthwhile if they only need to pay friends. It can be, especially when those friends already use it, but a payment-only alternative may be simpler if you will not touch the card or investing options. And if you are deciding whether to keep money in the app or cash it out, I would base that on how soon you plan to spend it and how much you prefer to manage through your bank, rather than leaving a balance there by default.
Overall, Cash App is a reliable, user-friendly option for managing your money efficiently. Whether you’re splitting a pizza bill or exploring cryptocurrency, this app has got you covered.
So, if you haven’t tried it yet, give it a shot. You might just find it becomes a staple in your financial toolkit, simplifying your transactions one tap at a time.
Frequently Asked Questions
01What is Cash App and how does it work?
Cash App is a mobile payment service that allows users to transfer money to one another using a mobile phone app. After downloading the app, you can link your bank account or credit card to send and receive money quickly. It also offers features like investing in stocks and Bitcoin.
02Is Cash App secure to use for financial transactions?
Yes, Cash App employs several security measures to protect your financial information. It uses encryption and fraud detection technology, and users are encouraged to enable additional security features like two-factor authentication and PIN entry. However, it's essential to stay vigilant and not share your account details with others.
03Are there any fees associated with using Cash App?
Cash App generally offers free services for basic transactions, such as sending or receiving money from friends. However, there are fees for some transactions, like instant transfers to a bank account or using a credit card for payments. Always check the app for the most current fee information.
04Can I use Cash App for international transactions?
Currently, Cash App is only available for users within the United States and the United Kingdom. Transactions between these two countries are possible, but international transfers beyond this are not supported. If you need to send money internationally, you might need to consider other services.
05What should I do if I encounter issues with Cash App?
If you experience problems with Cash App, you can contact their support team through the app by navigating to the support section. There’s also an extensive help section on their website to address common issues. For urgent concerns, reaching out via social media or email can provide additional support options.


